



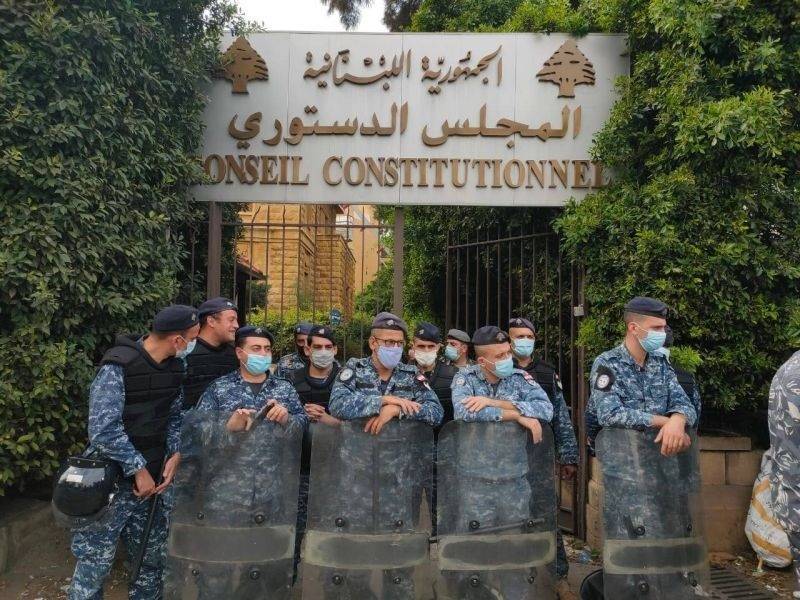
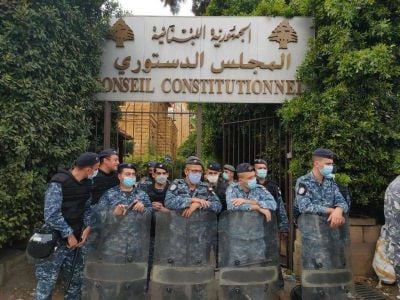
The entrance of the Constitutional Council headquarters in Hadath guarded by police officers during a demonstration in December 2024. (Credit: Claude Assaf/L’Orient-Le Jour)
Badih Moukarzel is an attorney-at-law and former public law teaching assistant at Saint Joseph University of Beirut (USJ)
Law No. 71/2026 on the banking sector’s reform and restructuring was challenged by President Joseph Aoun before the Constitutional Council, but only with regard to Article 3.
This article deliberately omits any reference linking the law and the new chamber of the Higher Banking Commission to the Code of Money and Credit.
Since its enactment in 1963, the Code has served as the cornerstone of the legal framework governing the country’s banking sector.
Since then, every legislation adopted to regulate the banking and financial sectors have been linked to it, while the bodies established under these laws have been set up within Banque du Liban (BDL, central bank) and placed under the authority of the Code.
This banking reform and restructuring law is the sole exception. Its authors in Parliament deliberately sought to sever it from its legitimate legal foundation. More seriously, they linked it to a foreign framework whose scope and consequences they do not fully understand.
In the version amended by the Cabinet and submitted to Parliament, Article 3 tasks the chamber of the Higher Banking Commission with applying, without providing any further details, “international standards” in the restructuring of Lebanese banks.
No one is disputing the principle of such standards, including BDL itself. However, their content, the way they are to be applied, and even their origin remain undefined, given the wide range of international standards and frameworks available.
The regulator’s role
Strangely and regrettably, the Finance and Budget Committee, which was the first to review the draft law and includes representatives of all parliamentary groups, had deemed it necessary to add a reference to the Code of Money and Credit alongside the reference to international standards. This addition was intended to ensure the law’s consistency, clarity and integration into the broader body of legislation governing this sovereign sector.
Most importantly, this would at least have enabled BDL to fully exercise its role as the national regulator of the banking sector and its restructuring, rather than being relegated, as the parliamentary vote intended, to the position of an engaged observer bound by undefined international standards.
At this late stage in the legislative process, I will not engage in a futile debate over a law passed amid widespread confusion, by a show of hands, by MPs eager to bring the matter to a close, having come to see the legislation as more of a popular constraint than a national duty to legislate rigorously.
Instead, I will simply recall a few fundamental principles of constitutional law, based on the Constitutional Council’s case law on constitutional review of legislation
Incomplete, unclear and incoherent
It is well-established in the case law of both the Lebanese Constitutional Council and the French Constitutional Council that a law that fails to define the scope of its own authority is unconstitutional because the legislators have not fully exercised the powers conferred upon them by the Constitution.
In other words, by adopting a law or provision that is too vague, incomplete or imprecise, and leaving the matter to be decided by another, unspecified authority or by international standards, the legislative body would be guilty of failing to fully exercise its constitutionally mandated powers — a doctrine known in French law as negative incompetence.
By making the implementation of Article 3 of the law in question subject to international standards without defining those standards or specifying which national authority is empowered to lay down clear and precise rules for their application, the Lebanese legislator has failed in its constitutional duty to legislate.
In doing so, it has abdicated its sovereign legislative authority to determine the rules governing the international standards it voted to incorporate into the law. For these reasons, Article 3, as adopted, is incomplete, unclear and incoherent.
It is incomplete because it fails to identify the reference frameworks governing these international standards, does not establish the standards itself, and does not, where appropriate, designate the national authority responsible for selecting the applicable international standards
Article 3 is unclear because it creates confusion by introducing a reference to international standards without clearly explaining how they are to be reconciled with the other applicable provisions of the Code, which the law does not appear to exclude; quite the contrary.
Article 3 itself establishes a two-tier system under the Higher Banking Commission, a clear indication that the Code of Money and Credit is the legal basis for this institutional structure.
The same applies to the appointment of the members of this chamber, which is chaired by the governor of BDL and includes, among others, the first deputy governor and the chair of the Banking Control Commission, all affiliated with the central bank and whose powers are defined by the Code and the laws from which they derive.
Legislative void
Doesn’t Article 70 of the Code entrust BDL’s Central Council with the exclusive role of defining the policy for safeguarding and protecting the country’s financial and monetary system?
This Central Council is not the sole preserve of the governor, but consists of deputy-governors representing various religious communities, appointed and authorized by the Cabinet, as well as the statutory directors-general of the Ministries of Finance and Economy, along with a government commissioner.
It would have been clearer for Parliament to align the Code’s core provisions with international standards, which have become something of a mirage: everyone in Parliament talks about them, but no one sees or reads them.
Finally, Article 3, as drafted and adopted by Parliament, is itself incoherent. This stems from the fact that the body of legislation contained in the Code of Money and Credit is left facing a legislative void that international standards cannot fill.
No law can delegate its legislative function to foreign, undefined substitutes operating in a vacuum and not established or incorporated into the law itself.
Article 3 is incoherent because it lacks a link to a national legal framework, effectively sidelining the Code in the application of the law’s substantive provisions. Parliament has thus failed to fully exercise its constitutional powers, a failure the Constitutional Council should recognize and sanction.
Historical denialism
In our view, the Lebanese MPs’ open abandonment of their constitutionally mandated legislative powers reflects another intellectual failure: one that amounts to both historical and political denialism.
First, it is a form of historical denialism, as it denies BDL and the Code of Money and Credit the historical role they have played in shaping the country’s banking system from its establishment in 1963 to the present day.
This is a legacy that brought Lebanon prosperity and placed its banking system among the world’s most respected, successful and sought-after. History may not repeat itself, but it cannot lie.
Lebanon experienced its golden age under the auspices of its banking system, regulated for decades by BDL and governed by the Code of Money and Credit, which continues to govern the sector to this day.
Historical truth also demands recognition of the mistakes made by the former governor, who remained in office for 30 years — or, more precisely, five consecutive terms, each renewed by successive governments with the approval of past and present MPs.
The problem lies not in the Code itself, but in its rejection and repeated distortion by those who have repudiated it. Past and present MPs have been living witnesses to this. Refusing to acknowledge this historical truth is itself a form of denial: parliamentary denialism.
A sense of infallibility
The passage of this banking reform and restructuring law is another example of the political denialism unfolding before our eyes.
The law was first passed by Parliament in August 2025 and subsequently challenged by MPs before the Constitutional Council, which was asked to review it and partially annul it. The Council upheld the law, making minor revisions, but, more importantly, retained Article 3, which explicitly referred to the Code of Money and Credit.
The law remained in force from August 2025 until August 2026, when it was amended following the submission of a new bill by the very same government that had drafted the previous year’s law
The very same MPs who voted for the previous law have now voted for the new one, but without the Code. Those celebrating victory today should remember that a year ago, they too had victory on their side — and the Code to boot.
The problem, then, lies not in the Code but in the MPs themselves, who have just engaged in blatant political denialism.
Legal judgment does not stem from a sense of infallibility — as the recklessness of some might lead one to believe — but from the revealed truth to which everyone should submit.
This article originally appeared in French on L'Orient-Le Jour and was translated by Joelle El Khoury.
 7 p.m. recap: Aoun rejects leniency toward Hezbollah, Qatar eyes 2 power plants in Lebanon, Gantz bows out